Cash flow is where most small businesses actually live or die, not in the big strategic decisions, but in whether there’s enough in the account to cover wages, pay suppliers and keep the lights on while invoices are still sitting unpaid. It sounds basic, yet it’s consistently one of the most common reasons otherwise profitable businesses get into trouble.
So for this week’s edition of Let’s Talk, we put the question to a handful of business owners and experts: which cash flow habits and tools actually keep things stable?
Here’s what they told us.
Jeremy Vo, Co-founder and CEO, Piper
“Cash flow is the lifeblood of any small business, and the habits that keep it stable are often simpler than people think.
First, make cash flow forecasting a weekly ritual. You don’t need sophisticated software to do this—a simple spreadsheet that tracks expected income and outgoings for the next 4–8 weeks gives you enough runway to spot problems before they become crises. The discipline of updating this weekly forces you to stay connected to your financial reality.
Second, invoice immediately and follow up relentlessly. Every day an invoice sits unsent is a day you’re financing your customer’s business. Set a personal rule: invoice on the day of delivery, and automate reminders so outstanding invoices get chased at 7, 14, and 21 days.
Third, build a cash buffer. Aim for 8–12 weeks of operating expenses sitting in a separate account. This isn’t idle money—it’s insurance against slow payment months, unexpected expenses, or the seasonal dips that catch unprepared businesses off guard.
Finally, separate your business and personal finances completely if you haven’t already. Mixing them is the single biggest source of cash flow confusion I see in small businesses. Clean separation makes forecasting accurate and tax time far less painful.
The tools matter less than the habits. We built Piper to make cash flow forecasting effortless for small businesses, but the underlying discipline—knowing your numbers, staying ahead of receivables, and keeping a buffer—works whether you’re using a napkin or sophisticated software.”
Beau Bertoli, Co-Founder & Chief Revenue Officer, Prospa
“For small businesses, cash flow stability starts with visibility. You need to know exactly what’s coming in and going out—not just this month, but over the next quarter. Yet many business owners are still managing this in their heads or through a basic spreadsheet, which leaves them vulnerable to surprises.
The most effective habit I see among financially stable small businesses is a consistent cash flow review routine. Set aside time each week—even just 30 minutes—to review your cash position, upcoming commitments, and outstanding receivables. This simple habit gives you early warning signals and time to act before issues escalate.
On the tools side, accounting platforms like Xero or MYOB are a baseline, but the real value comes from connecting them with a cash flow forecasting tool so you can see projected balances based on your actual invoices and payment patterns. This removes the guesswork.
One often overlooked habit is building a buffer and then protecting it. At Prospa, we often see business owners dip into their buffer for non-essential expenses and then find themselves scrambling when a large bill hits or a customer pays late. Treat your buffer like a rule: replenish it as a priority when it’s drawn down, and don’t tap it unless it’s truly necessary.”
Morgan Wilson, Founder & Director, creditte accountants & advisors
“The cash flow habits that separate stable small businesses from those constantly firefighting come down to a few fundamentals that most business owners know but don’t consistently apply.
The first is separating cash flow management from profit management. A business can be profitable on paper and still run out of cash. Understanding the timing difference between when you earn revenue and when you actually receive it is critical. I always encourage clients to manage their ‘cash flow P&L’ alongside their accounting P&L.
Second is proactive debtor management. This doesn’t just mean chasing invoices—it means shortening payment terms where possible, offering early payment incentives, and having clear, firm processes for overdue accounts. The businesses that struggle most with cash flow often have the weakest follow-up processes on outstanding invoices.
Third is a rolling 13-week cash flow forecast. Updated weekly, this tool is the single most powerful thing a small business can do to stay ahead of cash flow problems. It forces you to think forward, not just react to what’s already happened.
On the tools side, the platform matters less than the discipline. Xero, MYOB, and QuickBooks all have solid cash flow tools. The key is connecting them to your bank feeds and reviewing them regularly—not just at tax time.
Finally, build a cash reserve equivalent to at least six to eight weeks of operating costs. This buffer is what allows businesses to weather delayed payments, unexpected costs, or quiet trading periods without entering crisis mode.”
Ryan Williams, Director, Australian Centre for Business Growth
“Cash flow challenges are one of the most common reasons small businesses struggle to scale, even when they’re profitable. The businesses that maintain stability tend to share a few key habits.
The most important is having a forward-looking cash flow forecast—not just a backward-looking view of what’s already happened. A 13-week rolling forecast, reviewed weekly, lets you see problems before they arrive and make proactive decisions rather than reactive ones.
Tight debtor management is equally critical. Invoice promptly, set clear payment terms, and have a systematic follow-up process. Many business owners avoid the uncomfortable conversations around outstanding payments, but that discomfort costs them dearly in cash flow terms.
On the tools side, any reputable accounting platform connected to your bank feeds gives you a solid foundation. Where businesses get real leverage is when they add a dedicated cash flow forecasting layer—whether that’s a purpose-built tool or a well-maintained spreadsheet model—so they can scenario-plan around different payment timing and sales outcomes.
The underlying principle is simple: cash flow stability comes from visibility and discipline, not from any single tool or tactic.”
Deb Rowling, Bookkeeper & BAS Agent, Aussie Bookkeeping Basics
“Keeping your cash flow stable as a small business owner comes down to a few solid habits and using the right tools. Here are my top tips:
Know your numbers: Review your cash flow statement regularly—weekly if possible. Understand what’s coming in, what’s going out, and when.
Invoice promptly and follow up: Send invoices as soon as work is done and have a clear system for chasing overdue payments. The longer an invoice sits unpaid, the harder it becomes to collect.
Separate your business and personal finances: This one sounds basic, but you’d be surprised how many small business owners are still mixing the two. A dedicated business bank account makes tracking cash flow far simpler.
Build a cash buffer: Aim to keep at least one to three months of operating expenses in reserve. This is your safety net for slow periods or unexpected costs.
Use cloud accounting software: Tools like Xero, MYOB, or QuickBooks give you real-time visibility of your financial position and can connect to your bank for automatic reconciliation.
Cash flow problems rarely appear overnight—they build slowly. The business owners who stay stable are the ones who keep a close eye on their numbers and act early when something looks off.”
Bart Wolkowski, Founder, King Work
“Cash flow stability in a small business isn’t about having a lot of money—it’s about having visibility and control over the timing of money moving in and out.
The habits that matter most are the unglamorous ones. Invoice immediately. Chase outstanding payments systematically. Review your cash position weekly, not monthly. Know exactly what’s due in the next 30, 60, and 90 days—both payables and receivables.
One of the most underrated habits is negotiating payment terms strategically. Push to collect from customers as quickly as possible while paying suppliers on the longest terms they’ll accept. That gap—between when cash comes in and when it goes out—is your working capital cushion.
For tools, cloud accounting software with bank feeds is the non-negotiable starting point. From there, a simple cash flow forecast—even just a spreadsheet mapping out the next 12 weeks—gives you enough forward visibility to make confident decisions rather than reactive ones.
The businesses I’ve seen struggle most with cash flow are the ones that only look at their bank balance. The ones that thrive treat cash flow forecasting as a core business discipline, not an afterthought.”
Nick Lim, Founder and Broker, Switchboard Finance
“For small businesses, cash flow stability comes from building the right habits early—before the pressure hits.
The most important habit is a weekly cash flow review. Not monthly, not quarterly—weekly. Sit down every Monday, look at what’s coming in this week, what’s going out, and what the next four weeks look like. This one habit alone gives you enough lead time to take action before a cash shortfall becomes a crisis.
Alongside that, get your invoicing tight. Invoice on the day you complete work. Set payment terms clearly—and enforce them. Automate reminders for overdue invoices so the follow-up process doesn’t rely on you remembering to chase people.
On the tools side, cloud accounting software connected to your bank is the foundation. Xero and MYOB both do this well for Australian businesses. If you want a layer of cash flow forecasting on top, tools like Float or Futrli connect directly and give you a visual runway of what’s coming.
One habit that often gets overlooked: understand the timing mismatch in your business. If you’re paying suppliers before you collect from customers, that gap is your cash flow risk. Knowing that gap—and managing it actively—is what keeps businesses stable when growth accelerates.
Finally, don’t wait until you need finance to arrange it. Having a line of credit or overdraft facility in place before you need it means you’re borrowing from a position of strength, not desperation.”
David Caruso, Founder & CEO, BuyFactory.direct
“Cash flow is the single most important metric for any small business, and the habits that keep it stable are often the least glamorous ones.
The first habit is visibility. You cannot manage what you cannot see. Whether you’re using accounting software or a spreadsheet, you need a real-time picture of what’s in your account, what’s owed to you, and what you owe others. I review our cash position every single morning—it takes five minutes and keeps me ahead of problems.
Second is invoicing discipline. Invoice immediately when work is completed or goods are delivered. Every day of delay is a day you’ve given your customer an interest-free loan. Set clear payment terms and enforce them consistently.
Third is separating your tax obligations from your operating cash. As soon as revenue comes in, set aside the GST component and your estimated income tax. Treat it as untouchable. The businesses that get into the most trouble are those that spend money that was never really theirs.
On the tools side, any cloud accounting platform with bank feeds is a good foundation. For businesses that carry inventory, the discipline of matching purchase orders to cash flow forecasts before committing is essential—buying inventory ties up cash, and if it doesn’t sell quickly, that cash stays locked up.
The underlying principle is simple: cash flow problems are rarely sudden. They build slowly from bad habits—delayed invoicing, ignoring overdue accounts, spending tax money. Fix the habits, and the cash flow follows.”
Kylie Bishop, Founder & MD, Incredible U
“Cash flow is one of those areas where small businesses either thrive or struggle, and the difference usually comes down to habits rather than resources.
My top three tips:
Invoice immediately and follow up consistently. Don’t wait until the end of the month or until you remember. Invoice on completion, set clear payment terms, and have an automated follow-up sequence for overdue accounts. The sooner the invoice is out, the sooner you get paid.
Keep a rolling 90-day cash flow forecast. This doesn’t need to be complicated—a simple spreadsheet mapping expected income and outgoings for the next 12 weeks gives you enough forward visibility to make smart decisions. Update it weekly.
Build a cash reserve and protect it. Aim for at least 6–8 weeks of operating expenses sitting untouched in a separate account. This buffer gives you room to breathe when a client pays late or an unexpected expense hits.
For tools, cloud accounting software connected to your bank is the non-negotiable starting point. Beyond that, the best tool is the discipline to actually look at your numbers regularly—not just at tax time.”
Dev Punjani, Chartered Accountant and Director, Credible Accounting
“The cash flow habits that keep small businesses stable are deceptively simple: know your numbers, invoice promptly, and always be looking ahead rather than behind.
The most common mistake I see is business owners managing cash flow reactively—checking the bank balance when they need to make a payment rather than forecasting what’s coming. A 13-week rolling cash flow forecast, reviewed weekly, shifts you from reactive to proactive. It gives you the runway to spot shortfalls early and take action—whether that’s accelerating collections, delaying non-essential spending, or arranging a short-term facility.
On the tools side, cloud accounting software with bank feeds is the foundation. Xero, MYOB, and QuickBooks all provide solid cash flow reporting. The key is using these tools consistently—reconciling regularly, reviewing reports weekly, and not just logging in at BAS time. The data is only useful if you’re actually looking at it.”
Chloe Bowman, Service Enablement Manager, ADP
“For small businesses, cash flow stability starts with understanding your payroll obligations clearly and building them into your cash flow forecast as a fixed, non-negotiable commitment.
Payroll is often the largest and most predictable cash outflow a small business has—yet many owners treat it as an afterthought in their cash flow planning. Knowing exactly when payroll falls due, what the total obligation is including super and PAYG withholding, and planning your cash position around those dates is one of the simplest and most impactful habits you can build.
The second habit is separating tax obligations from operating cash. Set aside PAYG withholding and super contributions as soon as you process payroll, rather than treating that money as available working capital. Businesses that commingle these funds often find themselves in difficulty when payment dates arrive.
On the tools side, integrated payroll and accounting platforms that automatically calculate liabilities and connect to your cash flow forecasts remove a significant source of manual error and give you a cleaner picture of your true cash position at any given time.”
Felipe Chaparro, Founder, SYSBILT
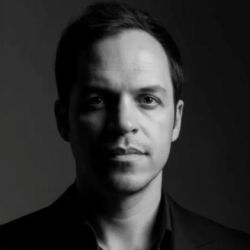
“In the construction and built environment sector, cash flow is notoriously difficult to manage—progress payments, retention, and long project timelines create constant pressure. The habits that keep cash flow stable are the ones that create structure around an inherently unpredictable environment.
The first habit is project-level cash flow forecasting. Every project should have its own cash flow map—when payments are due, when costs will be incurred, and what the net position looks like at each stage. This visibility allows you to identify cash flow gaps before they appear and negotiate payment milestones accordingly.
The second is aggressive management of payment claims. In construction, the right to make a payment claim and the discipline to exercise it promptly is everything. Delay your claim and you delay your payment cycle by an entire month. Invoice on time, every time.
For tools, project management software that integrates with your accounting platform is the most powerful combination in this sector. When your project costs and billings feed directly into your financial reporting, you get real-time visibility across the whole business—not just project by project.”
Michael Russell, Managing Director and Senior Finance Broker, Finwave Finance
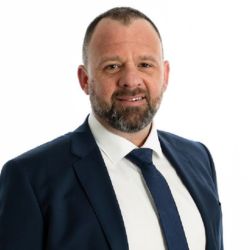
“Cash flow stability for small businesses comes from a combination of proactive habits and having the right financial infrastructure in place before you need it.
The most important habit is a consistent cash flow forecasting routine. A 13-week rolling forecast, updated weekly, gives you visibility of what’s coming and time to respond before a gap becomes a problem. Most business owners review cash flow too infrequently and too reactively.
The second habit is separating your working capital from your operating account. Money earmarked for tax, super, or a cash buffer shouldn’t be sitting in the same account as money you’re spending day-to-day. The psychological separation of having funds in different accounts makes it significantly less likely you’ll accidentally spend money that’s already committed.
On the tools and facilities side, understanding how a line of credit works here is valuable for small businesses—having one in place before you need it means you can access working capital quickly when timing mismatches occur, without having to arrange finance under pressure.
The businesses that stay stable through growth are the ones that have built their cash flow infrastructure early—the forecasting habit, the account structure, and the finance facilities—so they’re never scrambling when cash gets tight.”
Parteak Virmani, Business Services Manager, Polyglot Group
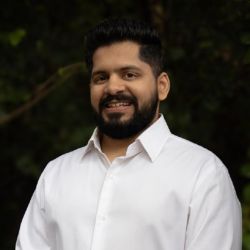
“Maintaining stable cash flow is critical for small business survival and growth. Here are the key habits and tools that make a real difference:
Regular cash flow forecasting: Create and maintain a 13-week rolling cash flow forecast. Update it weekly to reflect actual performance and adjust projections. This forward visibility is what separates businesses that react to cash flow problems from those that prevent them.
Prompt invoicing and active debtor management: Invoice immediately upon completing work or delivering goods. Implement a systematic follow-up process for outstanding invoices—automated reminders at 7, 14, and 21 days overdue significantly reduce average debtor days.
Strategic payment terms: Negotiate to receive payment from customers as quickly as possible while paying suppliers on the longest terms they’ll accept. This working capital gap management is one of the most powerful cash flow levers available to small businesses.
Dedicated tax and super accounts: Set aside GST, PAYG withholding, and superannuation into separate accounts as soon as revenue is received. Treating these obligations as untouchable eliminates one of the most common sources of cash flow crisis for small businesses.
Cloud accounting with bank feeds: Platforms like Xero or MYOB connected to your bank accounts provide real-time visibility of your cash position and dramatically reduce the time spent on reconciliation.
Access to working capital facilities: Establish a line of credit or business overdraft before you need it. Having finance available means you can manage seasonal fluctuations or growth-related cash gaps without disrupting operations.
The foundation of cash flow stability is discipline and visibility—knowing your numbers, acting on them consistently, and building the financial infrastructure to handle the inevitable bumps in the road.”
Leanne Berry, Partner Engagement Manager, MYOB
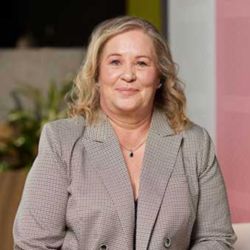
Know your cash flow position in real time
The first step to stable cash flow is visibility. Cloud accounting software connected to your bank feeds gives you an up-to-date picture of your cash position without manual data entry. With MYOB, for example, transactions flow in automatically, making reconciliation faster and your financial picture more accurate. If you’re still doing this manually, you’re always looking at yesterday’s numbers.
Invoice promptly and follow up systematically
Every day an invoice sits unsent is a day your customer gets an interest-free loan. Invoice on the day of completion, set clear payment terms, and use automated reminders for overdue accounts. The businesses that manage cash flow well are the ones that treat their accounts receivable process as seriously as their sales process.
Forecast ahead, not just behind
Most accounting tools show you what’s already happened. The real value is in forecasting what’s coming. A simple 13-week cash flow forecast—even in a spreadsheet—gives you enough runway to make proactive decisions. Many accounting platforms now have built-in forecasting or integrate with dedicated tools like Float or Futrli that connect to your existing data.
Protect your tax obligations
Set aside GST and income tax as soon as revenue hits your account. Treating these as untouchable removes one of the most predictable cash flow shocks small businesses face. Some businesses create a separate account purely for tax obligations—it’s a simple habit that prevents a lot of pain at reporting time.”
Nick Chong, Co-founder and Mortgage Adviser, Rateseeker
“For small business owners, cash flow problems are rarely about profitability—they’re about timing. You can be making great margins and still run out of cash if the money isn’t arriving when you need it.
The habit that makes the biggest difference is a weekly cash flow review. Not a monthly review, not a quarterly one—weekly. Sitting down every week to look at what’s coming in, what’s going out, and what the next 30 to 60 days looks like gives you enough lead time to take action before a gap becomes a crisis.
Alongside that, debtor management is critical. Invoice immediately, set clear payment terms, and follow up systematically. The businesses that struggle most with cash flow are often the ones that are too uncomfortable to chase outstanding invoices.
From a finance perspective, having a pre-arranged line of credit or overdraft facility is one of the most underutilised tools for small businesses. Most owners wait until they need finance to arrange it, which is the worst time to apply. Setting up a facility when your cash flow is healthy means you have a buffer available when timing mismatches occur—without the pressure of arranging finance in a hurry.
For tools, cloud accounting software with real-time bank feeds is the non-negotiable starting point. From there, a simple cash flow forecast—whether that’s a spreadsheet or a dedicated tool—gives you the forward visibility that a bank balance alone doesn’t provide.
The combination of the right habits and the right financial infrastructure is what keeps cash flow stable through the inevitable ups and downs of running a small business.”
Charlie Sheppard, Executive General Manager, Strategy & Operations, Xero
“Cash flow is consistently cited as one of the top challenges for small businesses—and for good reason. Even profitable businesses can fail if they run out of cash at the wrong moment. The habits and tools that prevent this share a common thread: they create visibility and reduce the time between earning money and receiving it.
The most impactful habit is regular cash flow forecasting. A 13-week rolling forecast, reviewed weekly, gives business owners the runway to make proactive decisions. At Xero, we’ve built short-term cash flow forecasting directly into the platform precisely because we see how powerful this visibility is for small business confidence and decision-making.
Alongside forecasting, the discipline of prompt invoicing and systematic follow-up on outstanding payments is one of the highest-ROI habits a small business can build. The average debtor days for small businesses are significantly higher than they need to be—and every day that improves translates directly into better cash flow.
The final piece is financial infrastructure: cloud accounting connected to bank feeds, automated reconciliation, and ideally a working capital facility arranged before it’s needed. Together, these create the foundation that lets business owners focus on growth rather than constantly managing cash flow anxiety.”
Keep up to date with our stories on LinkedIn, Twitter, Facebook and Instagram.